
Builder incentives are common on new construction in Virginia, but what is offered and how much is negotiable varies by builder, community, and market. The typical forms are mortgage rate buydowns, closing cost credits, upgrade and design center credits, and appliance packages. There is no guarantee of a specific discount, so the practical approach is to ask for the current written incentive offer and compare it against the same all-in cost.
Builder incentives in new construction: what they are, when builders offer them, and how to ask for them. The tips in this video are informational and fair-housing compliant: incentive offers vary by builder, community, and market, and no specific outcome or savings is guaranteed.
If you have toured model homes in Fredericksburg, Stafford, Spotsylvania, or any of the counties this site covers, you have likely seen incentive offers in the sales center: a banner for closing cost assistance, a rate buydown tied to the builder's lender, or a credit toward design center selections. These offers are real, and they are one of the few parts of a new construction purchase where there is usually room to talk. This guide covers what the typical incentives are, when builders offer them, how to ask, and which parts of the deal tend to stay firm.
One ground rule before the details: the on-site sales representative works for the builder, and a buyer's agent registered on your first visit works for you. Whatever you discuss, make sure the agreed terms end up in writing in the contract, because anything left out of the paperwork did not happen.
1. What Builder Incentives Typically Are
Builder incentives come in a handful of standard forms. Knowing what each one does for you is the first step to comparing offers fairly.
- Rate buydowns. The builder pays points up front to lower your mortgage interest rate, often through a temporary 2-1 buydown that reduces the rate for the first two years. A lower note rate lowers your monthly payment, so confirm how long the reduced rate lasts and exactly what the rate becomes afterward.
- Closing cost credits. The builder applies a set dollar amount toward your closing costs and prepaids, which reduces the cash you need at the table. These are often tied to using the builder's preferred lender, so compare the full package against an outside lender's quote before you commit.
- Upgrade and design center credits. A credit or allowance toward your design center selections, such as countertops, flooring, cabinetry, and fixtures, lets you upgrade finishes without paying the full retail difference out of pocket.
- Appliance packages. Builders sometimes include or credit appliances, flooring, or finishing packages. Their value depends on whether you would have bought those items anyway, so weigh the package against a simple cash credit for your own situation.
2. When Builders Offer Incentives
Incentives are not random. Builders tend to sweeten offers at predictable moments, and recognizing those moments helps you time your question.
- Inventory homes. Quick move-ins, spec homes, and model homes already built or nearly finished are the listings builders most want to clear, and they are where the deepest incentive offers tend to appear.
- Sales deadlines. Builders operate on quarterly and annual sales targets, so offers often grow toward the end of March, June, September, and December, and during community sales events.
- Final phases. As a community sells through its last phase, builders may add incentives to finish the remaining homesites rather than carry them into a new phase or market.
- Slower market periods. When buyer demand softens or inventory rises, incentives become more common across the market. The reverse is also true: in a fast-selling phase with strong demand, builders have less reason to offer concessions.
3. How to Ask About Builder Incentives
Asking well is mostly about getting the offer in writing and comparing it on the same basis. These steps keep the conversation productive:
- Ask for the current written incentive sheet. Builders publish incentive packages for each community and phase. Ask for the sheet in writing, including any expiration date, so you are negotiating against the actual current offer rather than a remembered one.
- Ask what the incentive is tied to. Many of the largest incentives, especially closing cost credits and rate buydowns, are conditioned on financing through the builder's preferred lender. Ask directly whether the offer requires that lender, and what remains of the incentive if you bring your own financing.
- Ask how the incentive appears on the closing disclosure. Whether it shows up as a credit, a price reduction, or an allowance changes what it does for your loan amount and your taxes, so ask to see it in writing before you sign.
- Compare offers on the same all-in cost. A $15,000 closing cost credit on one home and a $15,000 design center credit on another are not the same deal. Compare the total price, the incentive type, the rate, and the closing costs together so you can judge which package is genuinely better for you.
- Get every agreed item in writing. The type, the dollar value, any lender requirement, and any condition that could change it all belong in the contract. An incentive that is only mentioned in conversation is not part of your deal.
4. What Is Usually Not Flexible
Knowing where the room is not is just as useful as knowing where it is. These items tend to stay firm:
- The base price. Some builders publish a low base price and hold it firm by policy, preferring to move value through incentives instead. Ask directly whether the base price is adjustable so you are negotiating against the right assumption.
- Third-party costs. Title insurance premiums, recording and transfer fees, and settlement charges are set by the title company, county, and settlement agent rather than the builder, so they generally do not move.
- Lender-driven items. Mortgage rates move with the market, and lender-required fees like appraisal and credit report charges are set by the lender and its vendors. Shopping lenders, rather than asking the builder, is the way to affect those numbers.
- HOA and community fees. Monthly association dues and community assessments are set in the community documents and approved by the association, so they are not a per-buyer negotiation item.
Incentive offers vary by builder, community, and market
Everything in this guide is general information, not a promise of a specific outcome. Incentive types, values, and conditions differ from builder to builder, from community to community, from phase to phase, and they change as market conditions change. No particular discount, credit, or savings is guaranteed. The reliable route is to ask each builder for a written offer covering the current price, incentives, and any conditions, and to compare those offers on the same all-in cost.
Sources
The links below are independent sources that informed this guide. They are provided for reference and are not owned or controlled by this site.
- NewHomeSource: Negotiating Builder Incentives on how incentive offers work and what to watch for in the fine print.
- NewHomeSource: Negotiating the Purchase of a New Construction Home on what buyers can expect to negotiate when buying directly from a builder.
- National Association of REALTORS: Builders Are Sweetening the Deal with data on the share of builders offering incentives and discounts.
- Consumer Financial Protection Bureau: Find the Right Home covering new construction considerations, including builder deposits and financing.
- Barbara Jennings on YouTube: Negotiating Builder Incentives the featured video embedded above, with informational tips on asking for incentives on a new construction home.
Preferred Lenders
When an incentive is tied to financing, comparing the builder's preferred lender against an outside quote matters. Barbara works with two lending partners at Guaranteed Rate who serve new construction buyers across the Fredericksburg region: Mike Sanchez and Ken Melendez. Their full profiles, contact details, and videos are on the Preferred Lenders page.
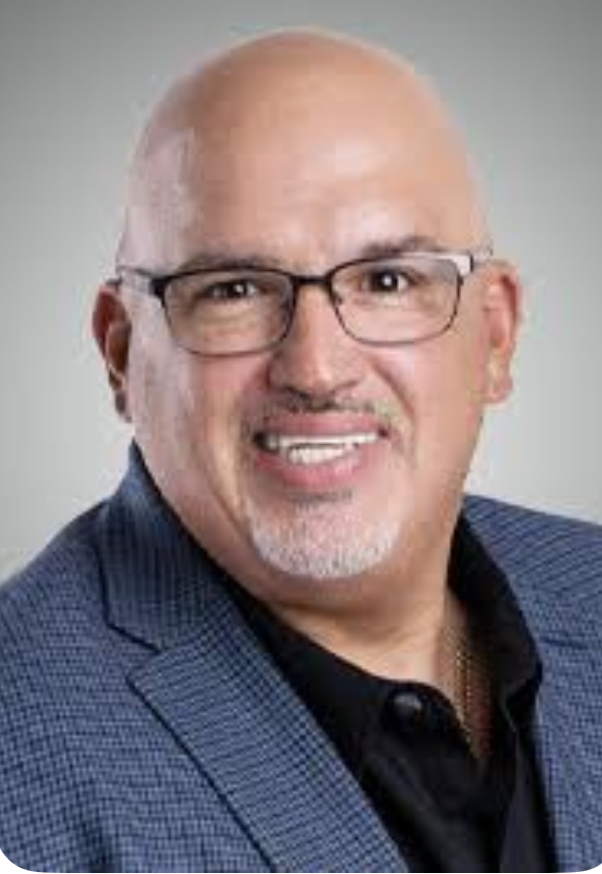
Mike Sanchez
Guaranteed Rate
NMLS #860048Branch Manager and Senior Vice President of Mortgage Lending at Guaranteed Rate, based in the Fredericksburg area, helping buyers find the right loan product from pre-approval through closing.
Meet Mike Sanchez, Guaranteed Rate (NMLS 860048).
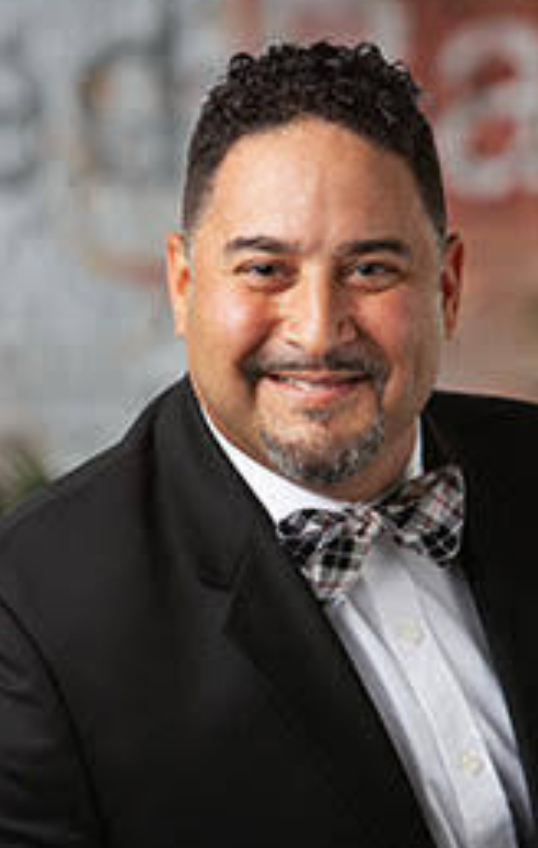
Ken Melendez
Guaranteed Rate
NMLS #2037924Vice President of Mortgage Lending at Guaranteed Rate, serving the Fredericksburg and Northern Virginia region with clear communication from pre-approval to clear-to-close.
Meet Ken Melendez, Guaranteed Rate (NMLS 2037924).
Ready to Compare Builder Incentives in Virginia?
Barbara tracks current incentive offers across Fredericksburg, Stafford, Spotsylvania, Orange, Fairfax, and Prince William County, and she can help you compare written offers on the same all-in cost. Contact her today for a consultation.